Corporate income tax
25%
Conditional SME rate: 20% on first €100,000 profit
Explore distribution, industrial partnerships and cross-border trade from a well-connected European location.
Start your journey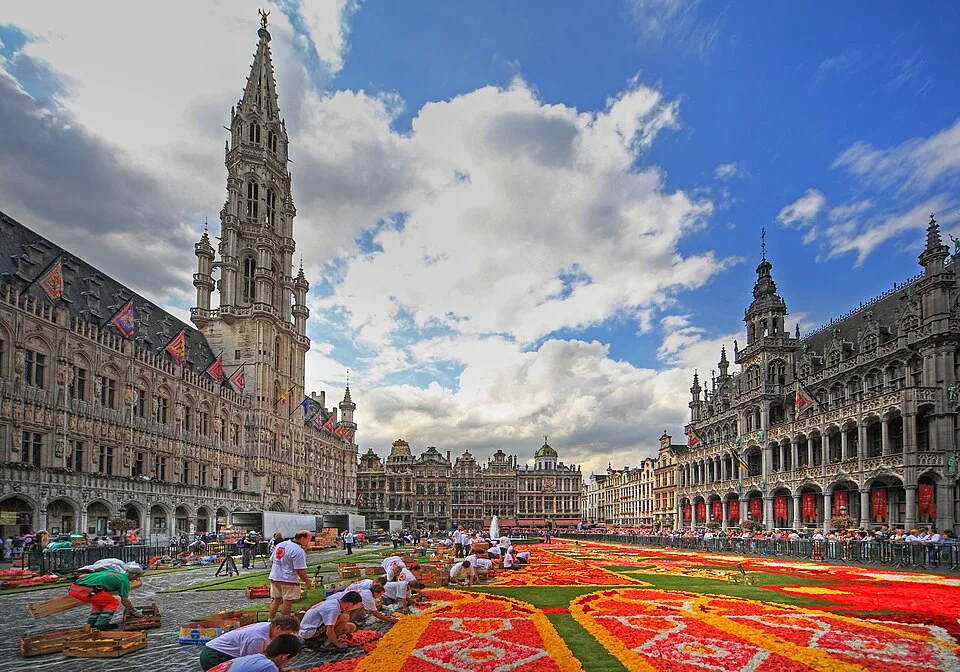
25%
Conditional SME rate: 20% on first €100,000 profit
21%
Reduced rates and exemptions depend on the supply
EUR
Euro
Professional card
Generally needed for non-EU self-employment; exemptions apply
The May 2026 Commission forecast projects 0.7% GDP growth in 2026. Subdued demand makes customer validation important. Choose your region with the customer base, language and local operating requirements in mind.
European Commission · May 2026 forecast (opens in a new tab)Start with a defined opportunity, then assess the route to market.
Explore importers and distributors with an existing customer base and suitable storage, compliance and delivery capabilities.
Flanders Investment & Trade (opens in a new tab)Assess supplier opportunities in chemicals, pharmaceuticals and advanced manufacturing against the buyer’s technical and quality requirements.
Compare regional support, premises, skills and customer proximity before selecting a base.
Taxes, establishment and the detail behind a commercial decision.
The standard rate is 25%. Qualifying small companies may receive 20% on the first €100,000 of taxable profit, subject to the applicable conditions.
PwC · Belgium corporate tax (opens in a new tab)Standard VAT is 21%. Include payroll costs, premises, accounting and local professional support in your operating model.
EU VAT rates (opens in a new tab)Non-EU nationals generally need a professional card unless exempt. The relevant region handles the process; the business case and residence position must be assessed together.
Belgian government · self-employment (opens in a new tab)Plan for the language of customers, staff and official administration. Establish the company, banking and registration requirements with local advisers.
Check your product’s HS code, origin, customs duties and applicable standards. Include freight, import VAT and distributor margins in the landed cost before choosing a route to market.
EU Access2Markets (opens in a new tab)Headline tax rates are not the total cost of operating. Reduced rates, sector rules, payroll obligations and large-group regimes may apply. Incorporation and permission to live or work are separate processes.
Begin with a customer or distributor shortlist, test the commercial terms and identify regional establishment requirements. Use those findings to decide the scale of your local presence.
Guidance that starts with your goals.
Define your market, customers and commercial objectives.
Prepare the relevant registrations and visa applications for your chosen route.
Move forward with your business and trade connections.
No. Company registration, ownership, residence and permission to work are distinct matters. The appropriate immigration route depends on your nationality, intended activity and eligibility.
That depends on your product or service, customers, budget and staffing needs. A distributor, commercial partnership, branch or locally established company may serve different objectives.
Tell us about your business. We’ll help you explore the next step.
Brussels · Grand-Place · Francisco Conde Sánchez · CC BY-SA 3.0. Resized, WebP format; cropped to fit the layout. The photograph retains its stated licence.
Last reviewed · Guidance for applicants and businesses based in India.